 |
| By | January 1, 2024 |
Homeowners insurance provides financial security and peace of mind during unforeseen circumstances. While insurance is essential, it’s also important to account for homeowners insurance costs. These have risen year-on-year, with an 11% rise from 2021 to 2022. Since these expenses may increase further in 2024, it’s vital to know how to reduce them. Here’s an overview of homeowners insurance and some of the best ways to reduce the associated costs. Factors Influencing Homeowners Insurance Costs Owning a home comes with great responsibility, and protecting it against potential risks is crucial. Homeowners insurance covers your home’s structural damages, personal belongings, and living expenses (in some cases). This safety net is necessary to secure your investment and prevent financial fallout. While the importance of homeowners insurance is undeniable, the rising costs can strain your budget. Here’s a deeper dive into ten factors influencing homeowners insurance costs: 8 Ways to Lower Homeowners Insurance The rising costs of homeowners insurance don’t have to leave you feeling helpless. Here are some practical ways to decrease those premiums and keep your budget intact: Compare Quotes Regularly Shopping around for insurance quotes might seem obvious, but it’s a step many homeowners overlook. Insurers adjust their rates occasionally, and new providers may…
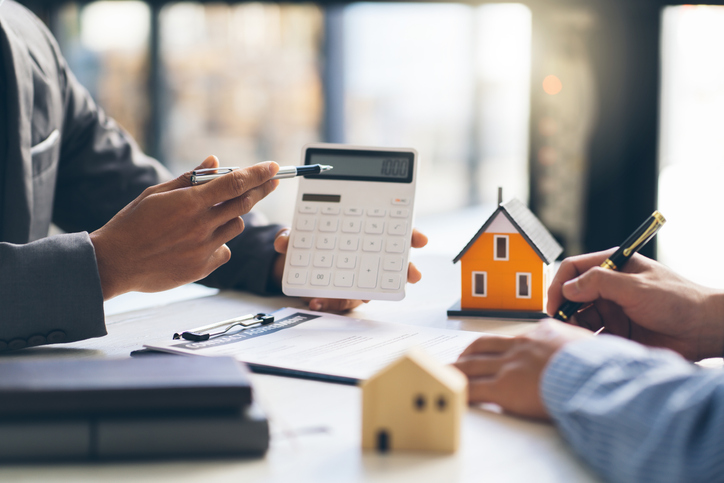
Homeowners insurance provides financial security and peace of mind during unforeseen circumstances. While insurance is essential, it’s also important to account for homeowners insurance costs. These have risen year-on-year, with an 11% rise from 2021 to 2022. Since these expenses may increase further in 2024, it’s vital to know how to reduce them.
Here’s an overview of homeowners insurance and some of the best ways to reduce the associated costs.
Factors Influencing Homeowners Insurance Costs
Owning a home comes with great responsibility, and protecting it against potential risks is crucial. Homeowners insurance covers your home’s structural damages, personal belongings, and living expenses (in some cases). This safety net is necessary to secure your investment and prevent financial fallout. While the importance of homeowners insurance is undeniable, the rising costs can strain your budget.
Here’s a deeper dive into ten factors influencing homeowners insurance costs:
- Location: Your geographical location plays a vital role in determining your homeowner’s insurance premium. Insurers may charge you more if you reside in an area prone to adverse weather events, like California or Florida. Additionally, areas with high crime rates or many claims can increase insurance costs.
- Size and Age of Your Home: Insurers consider the square footage when determining the potential cost of repairs or rebuilding. Larger homes typically translate to higher premiums as the magnitude of potential claims increases with the size of the property. It’s a simple equation—more space and risk translate to higher premiums. Similarly, older homes might require more maintenance and repairs. This can lead to potential claims and higher insurance costs.
- Home Condition: Regardless of your home’s age, its overall condition significantly impacts your premium. This includes homes with structural issues, outdated electrical systems, worn-out plumbing, or poor roof quality. If your inspection reveals significant issues, these costs can increase to adjust for added risks.
- Ownership and Financing: If you own your home outright, you have more flexibility with your insurance coverage. However, lenders often require borrowers to maintain a minimum level of coverage, impacting the premium.
- Level of Coverage: The more comprehensive your coverage, the higher your premium. This includes the amount of dwelling coverage, personal property coverage, and additional liability coverage. Some warranty insurance policies can also cover appliances and other systems. It’s essential to carefully consider what level of protection you need versus the cost of the premium.
- Deductibles: A deductible is the amount you agree to pay out of pocket before your insurer steps in. Opting for a higher deductible lowers your premium, but it also means you’ll shoulder more upfront expenses in case of a claim. Therefore, you should choose one you can comfortably afford without compromising your financial stability.
- Regulatory and Environmental Factors: Changes in local regulations or insurance laws can also affect homeowners insurance costs. For example, new building codes or environmental regulations may impact the cost of rebuilding your home and insurance premiums. Staying informed about any updates can help you anticipate potential changes in your policy.
- Additional Risks on Your Property: Unique features on your property, such as a pool, trampoline, or specific dog breeds, may heighten perceived risks. Insurers may require additional liability coverage for these features, potentially resulting in higher overall insurance costs. Investigating these unique aspects can let you assess your coverage needs.
8 Ways to Lower Homeowners Insurance
The rising costs of homeowners insurance don’t have to leave you feeling helpless. Here are some practical ways to decrease those premiums and keep your budget intact:
Compare Quotes Regularly
Shopping around for insurance quotes might seem obvious, but it’s a step many homeowners overlook. Insurers adjust their rates occasionally, and new providers may offer better deals. Regularly comparing quotes ensures you’re getting the most competitive rate available. Some insurance experts will simplify this process by providing a curated list of options after comparison.
Bundle Your Policies
Consider consolidating your insurance policies with one provider. Bundling your homeowners, auto, and other insurance needs can result in substantial discounts. It also simplifies your paperwork, making it a win-win.
Credit Score
In some states, insurers consider your credit-based insurance score to predict the likelihood of filing a claim. That’s why it’s vital to improve your credit score by managing debts responsibly and paying bills on time. This can lead to lower homeowners insurance rates and premiums. In addition, your credit score is a factor that extends beyond insurance and impacts various aspects of your financial life.
Review and Update Your Policy
Life changes, and so do your insurance needs. Periodically reviewing and updating your homeowner’s insurance policy is crucial. Consider any major renovations, additions, or changes in your personal property. Adjusting your coverage to align with your current circumstances ensures you’re not overpaying for unnecessary protection.
Maintain a Good History
Your past claims, mainly the frequency and type, can influence your homeowner’s insurance premium. A history of multiple claims can indicate a higher risk factor. Avoid making small claims that can potentially hike your premiums. If possible, handle minor repairs or replacements out of pocket. This way, you can maintain a clean claims history, positioning yourself as a lower-risk homeowner to insurers.
Consider Higher Liability Limits
While increasing your liability limit may raise your premium slightly, it can offer significant peace of mind. This is because liability coverage protects you financially in the case of injury and lawsuits. Imagine the financial burden of a lawsuit without adequate coverage.
Pay Annually
While most insurance companies allow monthly premiums, annual payments can sometimes offer discounts. This lump-sum payment can be a more manageable option for some homeowners and save you money in the long run.
Seek Professional Guidance
Navigating the complex world of insurance can be daunting. Seeking advice from insurance industry experts can help you choose a policy that fits your lifestyle. Many insurance companies offer discounts for various reasons, having a claims-free history, These experts will let you identify potential areas for cost savings. They can also guide you in making informed decisions about coverage levels and deductible amounts.
By implementing these strategies, you can take control of your homeowner’s insurance costs and keep them within your budget. You can make this process simpler by partnering with Cell Brokerage. Our home insurance experts will help you find the best policy and limit unnecessary expenses. Contact us today to learn more!
Talk to an Insurance Pro