 |
| By | April 15, 2024 |
There’s so much data floating around in the world today. We can use our cars or our smartphones, and in doing so, we create a digital footprint. Because of this massive collection of big data, industries are changing, and that includes the auto insurance industry. Insurance companies can harness big data to get even more knowledge about driver behavior, risks, and billing patterns. This creates new trends that shape auto insurance. Personalized Premiums with Telematics Auto insurance premiums used to merely be based on age, location, and driving history. While these remain important, big data allows insurers to dig deeper. Telematics, which is a technology that collects data on driving behavior through devices installed in vehicles, has brought this change out. Telematics devices installed in vehicles can collect a lot of data, including: This process is known as usage-based insurance (UBI). UBI works through a telecommunications network and analyzes the data. By using UBI, insurers can create more nuanced risk profiles for each driver. Safe drivers are rewarded with lower fares, while those who exhibit risky behavior may pay higher prices to offset their driving habits. This is all in the hopes of promoting safer driving so that there are…
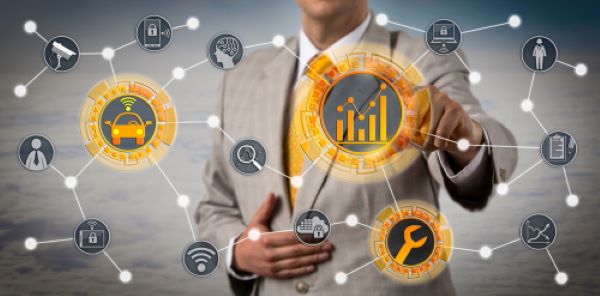
There’s so much data floating around in the world today. We can use our cars or our smartphones, and in doing so, we create a digital footprint. Because of this massive collection of big data, industries are changing, and that includes the auto insurance industry. Insurance companies can harness big data to get even more knowledge about driver behavior, risks, and billing patterns. This creates new trends that shape auto insurance.
Personalized Premiums with Telematics
Auto insurance premiums used to merely be based on age, location, and driving history. While these remain important, big data allows insurers to dig deeper. Telematics, which is a technology that collects data on driving behavior through devices installed in vehicles, has brought this change out.
Telematics devices installed in vehicles can collect a lot of data, including:
- Mileage driven
- Time of day driven (higher risk at night)
- Frequency of harsh braking or acceleration
- Whether the driver is attentive to road conditions
This process is known as usage-based insurance (UBI). UBI works through a telecommunications network and analyzes the data. By using UBI, insurers can create more nuanced risk profiles for each driver. Safe drivers are rewarded with lower fares, while those who exhibit risky behavior may pay higher prices to offset their driving habits. This is all in the hopes of promoting safer driving so that there are fewer accidents on the road moving forward.
A Holistic View of Risk
UBI is just the tip of the iceberg. Big data enables insurers to analyze a wide variety of data points to assess risk. This includes the following:
- External Data: Traffic, weather, accident history in specific areas, and crime rates in an area can all be used to create a comprehensive risk map.
- Vehicle Statistics: Information from the diagnostic system in the vehicle can reveal maintenance history, possible mechanical issues, and the vehicle’s safety.
- Social Media Data: While not always used directly in premium decisions, some insurers may consider publicly available social media data to understand a driver’s overall risk (which is kept private, of course, including relevant information).
Insurance companies can now make accurate risk assessments, resulting in fairer pricing for all policyholders. Furthermore, this information can identify areas where accidents are most likely to occur, allowing insurers to develop targeted safety measures and improve road management by local authorities in collaboration with local authorities.
Improved Risk Assessment and Mitigation
Big data lets insurers create a more accurate picture of individual drivers, which lets them give fairer pricing and more effective risk mitigation strategies in the following ways:
Real-Time Incident Response
Big data empowers insurers to respond faster to incidents. By using real-time accident and claims data, companies can streamline their response strategies, provide timely assistance to system owners, and minimize the impact of an incident all over the place.
Climate and Geographic Risk Assessment
The ability to handle a variety of issues allows professionals to assess weather and geographic risk better. This means that not only individual driving behavior but also external factors such as weather and local accidents must be considered.
Enhancing Customer Experience
Traditionally, premiums were based on broad categories, and customer service interactions were often impersonal. Big data is changing this by bringing a fresh era that is focused on customers in the following ways:
Targeted Discounts and Coverage Options
Insurance providers track how you drive and then offer personalized discounts on your coverage. If you use your car mostly on weekends or don’t drive much, they will identify these patterns. This might qualify you for substantial discounts, make your insurance more tailored to your habits, and save you money. This is different from someone who drives a lot every day.
How you drive can also help create insurance plans that fit your needs. For example, if you often use ride-hailing services, you could choose a policy that gives you less coverage when your car is parked but more protection when driving for yourself. It’s like having insurance that matches how you use your car!
Streamlining Connections and Immediate Assistance
Big data is like a behind-the-scenes ally, allowing companies to seamlessly understand and cater to your needs. Suppose you’re gearing up for a long road trip and receive a notification suggesting extra roadside assistance coverage. Or imagine earning a real-time discount on your premium simply by choosing a less congested route during rush hour. With big data, these personalized touches become possible, enhancing your overall experience.
Tailored Risk Management at Your Fingertips
Big data is not all about discounts; it opens the door to interactive risk management tools. Imagine an app analyzing your driving habits and offering instant feedback. This app could alert you to harsh braking or following too closely, guiding you to become a safer driver over time. It’s like a game where safe driving earns you rewards, putting you in control of your risk profile and potentially reducing your premium. This personalized approach not only incentivizes positive behavior but also empowers you to actively shape your insurance journey.
The Future of Auto Insurance
As big data continues to evolve, we can expect even more transformative changes in auto insurance:
- Hyper-Personalization: Insurance policies will be increasingly tailored to individual needs, taking into account factors such as driving habits, handling, and even weather rather than the policyholder.
- Focus on Prevention: If insurance companies better understand risks, they can provide incentives for maintenance and safety studies, leading the way to better safety management.
- Micro-Insurance: Big data can lead to flexible insurance options that can be purchased for specific periods or types of vehicles, meeting the changing needs of policyholders.
Big data is shaking up auto insurance! Get a personalized quote from Cell Brokerage and see how much you could save based on your driving habits. We’ll find the perfect coverage for you, not a one-size-fits-all policy. Save money, drive happy—get your quote today!
Talk to an Insurance Pro