 |
| By | January 15, 2026 |
Running a landscaping, lawn care, or gardening business is a rewarding but inherently risky venture. The daily work involves utilizing heavy, specialized equipment, often performing work around valuable client property, and engaging in demanding physical labor. This operational reality means that a variety of costly incidents, such as a misplaced rock damaging a window, an employee injury from machinery, or a lawsuit over alleged negligence, are constant threats to your financial stability. Landscapers’ insurance provides more than just a safety net; it offers tangible, strategic benefits that directly contribute to the success and growth of your business. By transferring the financial risk of accidents, injuries, and operational setbacks to an insurer, you gain the confidence to scale your operations, secure larger contracts, and focus on delivering high-quality service. Financial Protection and Risk Mitigation The most immediate benefit of commercial insurance is safeguarding your business’s assets against catastrophic financial loss. Professional Credibility and Contract Acquisition Insurance is often the key that unlocks larger, more profitable business opportunities. Promoting Operational Stability and Growth Insurance provides the stable operational platform necessary for long-term growth and expansion. Landscapers’ insurance is more than an obligation; it is a fundamental component of effective business management. By…
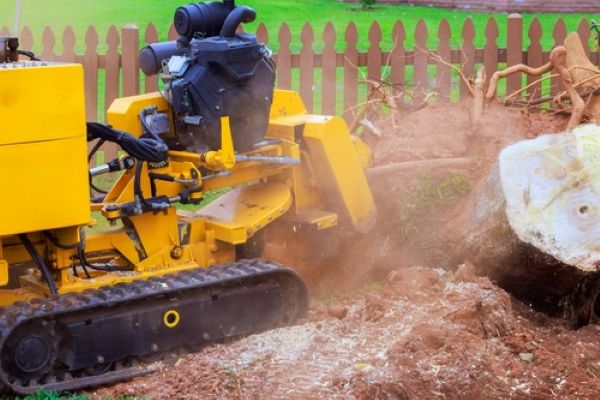
Running a landscaping, lawn care, or gardening business is a rewarding but inherently risky venture. The daily work involves utilizing heavy, specialized equipment, often performing work around valuable client property, and engaging in demanding physical labor. This operational reality means that a variety of costly incidents, such as a misplaced rock damaging a window, an employee injury from machinery, or a lawsuit over alleged negligence, are constant threats to your financial stability.
Landscapers’ insurance provides more than just a safety net; it offers tangible, strategic benefits that directly contribute to the success and growth of your business. By transferring the financial risk of accidents, injuries, and operational setbacks to an insurer, you gain the confidence to scale your operations, secure larger contracts, and focus on delivering high-quality service.
Financial Protection and Risk Mitigation
The most immediate benefit of commercial insurance is safeguarding your business’s assets against catastrophic financial loss.
- Protection from Liability Claims: General Liability (CGL) coverage is essential for covering claims of third-party bodily injury or property damage. This benefit is critical in landscaping, where you work directly on clients’ property. CGL can offset the cost of legal defense, settlements, and damages if your crew accidentally breaks a fence, damages a sprinkler system, or causes a customer to slip and fall on a job site. Without it, these high costs would come directly from your business funds.
- Safeguarding Your Equipment Investment: Landscaping equipment—mowers, trimmers, leaf blowers, and specialized installation tools—is expensive and constantly mobile. Inland Marine Insurance (Contractors Equipment coverage) protects these valuable assets if they are stolen, lost, or damaged while in transit or on a job site. This benefit allows you to replace or repair essential gear quickly, ensuring minimal operational downtime.
- Protecting Cash Flow from Injuries: Workers’ Compensation insurance shields your business’s cash flow from the high costs associated with employee injuries. It can cover the injured worker’s medical bills and lost wages, preventing these sudden, significant expenses from draining your profits.
Professional Credibility and Contract Acquisition
Insurance is often the key that unlocks larger, more profitable business opportunities.
- Meeting Client Requirements: Having adequate insurance is often a non-negotiable requirement for securing commercial contracts, working with property management firms, or taking on larger residential projects. Clients demand proof of liability coverage to protect their own interests. Carrying a comprehensive policy immediately makes your business competitive and eligible for top-tier work.
- Building Trust and Reliability: Professional insurance signals to clients that you are a serious, reliable business owner who takes responsibility for operational risks. This commitment to financial responsibility builds customer confidence and enhances your company’s reputation.
- Protecting Your Reputation: In the event of an unavoidable accident, insurance allows you to swiftly cover the damages and rectify the situation without prolonged disputes. This quick, professional response preserves your reputation and minimizes negative word-of-mouth that can damage a growing business.
Promoting Operational Stability and Growth
Insurance provides the stable operational platform necessary for long-term growth and expansion.
- Ensuring Business Continuity: Policies like Business Interruption coverage protect your revenue stream. If a covered loss—such as a fire at your main office or storage shed—forces a temporary shutdown, this benefit protects against lost income and ongoing expenses like rent and payroll. This critical protection prevents a single property loss from destroying your entire business.
- Protecting Against Legal Risk: Workers’ Compensation and General Liability policies shield your business from costly lawsuits. By providing a dedicated defense fund, these policies can prevent large legal judgments from draining your business capital and distracting you from daily operations.
- Simplified Management with a BOP: For many landscaping and lawn care businesses, a Business Owner’s Policy (BOP) provides a cost-effective and efficient way to secure essential coverages. By bundling General Liability, Commercial Property, and Business Interruption coverage, the BOP streamlines policy management, allowing you to focus more on your clients and less on administrative tasks.
Landscapers’ insurance is more than an obligation; it is a fundamental component of effective business management. By utilizing this powerful risk management tool, you secure your future, build greater trust with your clients, and cultivate the confidence needed to succeed in the competitive landscaping industry.
Talk to an Insurance Pro