 |
| By | October 15, 2023 |
Understanding loan contracts and insurance policies can pose considerable complexity, especially in distinguishing between loan amounts and insured amounts. Nonetheless, unraveling this intricacy holds significant importance for safeguarding what might be your most valuable asset. Taking a little extra time to understand the difference between loan amounts and insured amounts can help provide not only peace of mind but a better understanding of how your money is being used. This guide aims to equip you with essential insights, enabling informed decisions concerning your home insurance coverage. What Is a Loan Amount? A loan amount is a type of financial aid provided by banks or mortgage lenders to facilitate home acquisition. This sum encompasses not only the home’s purchase price but also various associated costs, including transaction fees, closing expenses, and often property taxes. It’s vital to recognize that this amount is not a grant but rather a financial commitment. While striving for homeownership, you will ultimately be required to reimburse this loan, typically with interest. However, to fully protect your investment, you must consider another crucial aspect: the insured amount. What Is an Insured Amount? An insured amount signifies the payment provided by your insurance company to support the restoration or repair…
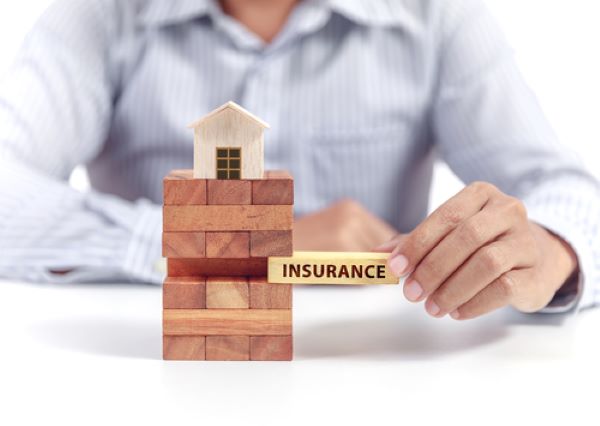
Understanding loan contracts and insurance policies can pose considerable complexity, especially in distinguishing between loan amounts and insured amounts. Nonetheless, unraveling this intricacy holds significant importance for safeguarding what might be your most valuable asset. Taking a little extra time to understand the difference between loan amounts and insured amounts can help provide not only peace of mind but a better understanding of how your money is being used.
This guide aims to equip you with essential insights, enabling informed decisions concerning your home insurance coverage.
What Is a Loan Amount?
A loan amount is a type of financial aid provided by banks or mortgage lenders to facilitate home acquisition. This sum encompasses not only the home’s purchase price but also various associated costs, including transaction fees, closing expenses, and often property taxes.
It’s vital to recognize that this amount is not a grant but rather a financial commitment. While striving for homeownership, you will ultimately be required to reimburse this loan, typically with interest.
However, to fully protect your investment, you must consider another crucial aspect: the insured amount.
What Is an Insured Amount?
An insured amount signifies the payment provided by your insurance company to support the restoration or repair of your home in situations like fires, storms, or theft. This calculation is meticulous to ensure you have the essential funds for home restoration in case of a calamity.
Here’s why understanding the insured amount is essential:
Accurate Protection
The insured amount should reflect the actual cost of rebuilding your home. This includes construction materials, labor, and other expenses for restoring your property to its pre-damage condition.
Coverage
Home insurance covers more than just your home’s structure. It also includes coverage for your personal belongings, liability protection in case someone gets hurt on your property, and funds for temporary living expenses if you need to vacate your home during repairs.
Regular Updates
The insured amount isn’t static. You should review and adjust it periodically to account for changes in construction costs, inflation, and any renovations or improvements you make to your home. Ensuring your insured amount keeps pace with these changes is important to maintaining adequate coverage.
Now, let’s explore why these two amounts are different and how to make sure you have the right coverage for your home.
Loan Amount vs. Insured Amount: What’s the Difference?
Navigating the world of loans and insurance can often feel like traversing a complex labyrinth. Amidst this intricate financial landscape, one area that frequently leads to confusion is understanding the disparity between the loan amount and the insured amount.
Loan Amount
This amount is the financial amount you secure from a bank or mortgage lender to facilitate the purchase of a home.
Lender Requirement
Mortgage lenders calculate this sum by considering the home’s purchase price, your creditworthiness, and your ability to make monthly mortgage payments. They require confidence in your capacity to repay the loan, along with interest.
Payment Responsibility
Borrowers repay the loan over a specified period, usually 15, 20, or 30 years, through monthly mortgage payments. These payments typically include both the principal (the loan amount) and the interest.
Coverage
The sum covers the cost of acquiring the home. However, it doesn’t consider other factors, such as the land’s value, property appreciation, or the expenses associated with rebuilding or repairing the house in the event of damage.
Insured Amount
The insured amount stated in your insurance policy is important for safeguarding your home. Its primary role is to provide financial security in situations of damage, destruction, or loss caused by unexpected events like natural disasters, fires, theft, or vandalism. Essentially, it ensures you have the financial means to recover and rebuild without facing overwhelming expenses.
Insurance Policy
You obtain this through a homeowners insurance policy. This coverage provides financial assistance for rebuilding or repairing your home, replacing personal belongings, covering liability claims, and supporting additional living expenses if you need to relocate temporarily due to home damage.
Calculation
This amount is determined by evaluating the anticipated expenses associated with reconstructing your home entirely. It encompasses construction expenses, materials, labor, and any enhancements or modifications to the property.
Protection
The insured amount ensures you have adequate resources to recover from unexpected events, such as fires, storms, theft, or other insured perils.
How to Determine the Right Insured Amount
Selecting the appropriate insured amount for your home is a pivotal decision with significant ramifications during times of necessity. Here are some factors to ponder:
Don’t Base It on Your Loan
Depending on your loan amount to establish your insured amount is a prevalent misunderstanding that should be strictly avoided. It is crucial to grasp that your loan amount does not encompass the actual expenses associated with rebuilding your residence.
Consider the Replacement Cost
The insured amount should align with your home’s replacement cost, indicating the expenditure required to reconstruct it entirely. To attain a precise estimate, you can seek guidance from a qualified appraiser or your insurance agent.
Include Additional Coverage
Also, remember to include coverage for your personal belongings, like your stuff inside the house, protection for potential legal issues (liability protection), and funds to cover living costs if you have to stay somewhere else during home repairs.
Regularly Review and Update
As time goes by, construction materials and labor costs can change. Make sure to review and update your insured amount periodically to ensure it remains adequate.
Invest in your future with Cell Brokerage, your trusted source for personal and commercial insurance coverage. Whether you’re safeguarding your home and loved ones or protecting your business assets and ventures, our experienced team is here to find solutions tailored to your unique needs. Request your personalized insurance quote and experience peace of mind with our comprehensive coverage. Contact us now!
Talk to an Insurance Pro