 |
| By | July 15, 2024 |
Running a business involves navigating a constant stream of challenges. From managing inventory to keeping employees happy, there’s always something to keep you on your toes. But what happens when an unexpected event throws a wrench into your operations? Business interruption insurance (BI) can be a valuable safety net in such situations. Let’s explore what business interruption insurance is, how it works, what it covers, and how to determine the right coverage for your business. What Is Business Interruption Insurance? Business interruption insurance is a type of insurance that covers the loss of income a business suffers after a disaster. This can include natural disasters, fires, or other significant events that force a business to temporarily halt its operations. Unlike property insurance, which covers the physical damage to the business, BI compensates for the income the business would have earned during the period of interruption. How Does Business Interruption Insurance Work? When an insured event occurs, business interruption insurance provides financial support to cover lost revenue. The coverage period usually begins when the event causes the business to close and ends when the business resumes normal operations. The policy might also cover the time it takes to rebuild or repair…
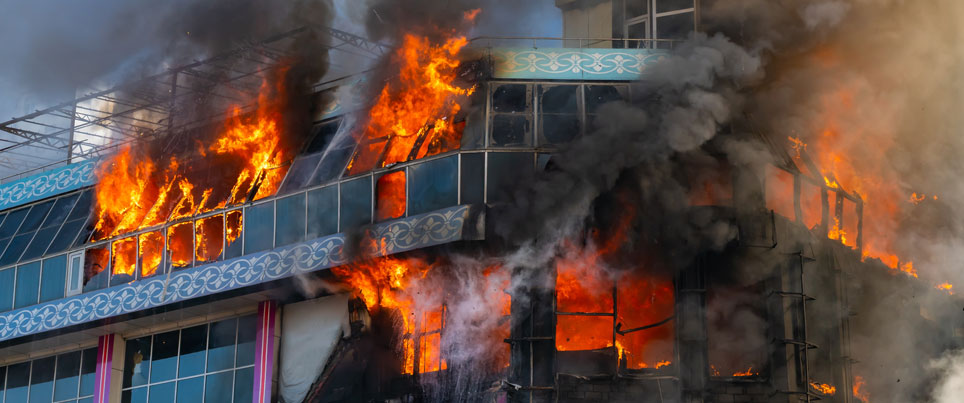
Running a business involves navigating a constant stream of challenges. From managing inventory to keeping employees happy, there’s always something to keep you on your toes. But what happens when an unexpected event throws a wrench into your operations? Business interruption insurance (BI) can be a valuable safety net in such situations.
Let’s explore what business interruption insurance is, how it works, what it covers, and how to determine the right coverage for your business.
What Is Business Interruption Insurance?
Business interruption insurance is a type of insurance that covers the loss of income a business suffers after a disaster. This can include natural disasters, fires, or other significant events that force a business to temporarily halt its operations. Unlike property insurance, which covers the physical damage to the business, BI compensates for the income the business would have earned during the period of interruption.
How Does Business Interruption Insurance Work?
When an insured event occurs, business interruption insurance provides financial support to cover lost revenue. The coverage period usually begins when the event causes the business to close and ends when the business resumes normal operations. The policy might also cover the time it takes to rebuild or repair the damaged property. This means the business can continue paying its bills, salaries, and other operational costs during the downtime.
Key Elements of Business Interruption Insurance
Knowing the core components of business interruption insurance can help you understand how it protects your business during unforeseen disruptions. Here are a few integral components:
Coverage for Lost Revenue
The primary component of BI is coverage for lost revenue. This is calculated based on the company’s financial records, including past performance and expected future earnings. Insurers typically examine the company’s profit and loss statements to determine the appropriate amount of compensation.
Operating Expenses Coverage
In addition to lost revenue, the insurance covers ongoing operating expenses, such as rent, utility bills, and payroll. This ensures the company can maintain essential operations and retain its staff even when it’s not generating income.
Extra Expenses Coverage
Some policies also cover extra expenses incurred to mitigate the impact of the interruption. For example, if a business needs to rent temporary office space or equipment to continue operations, these additional costs can be covered. This helps businesses resume operations faster and minimize the long-term effects of the interruption.
Key Things to Know about BI Coverage
Understanding the following aspects is important for navigating BI effectively:
- Not a Standalone Policy: BI coverage is typically an add-on or endorsement to a property insurance policy. This means you’ll need a property insurance policy to qualify for BI.
- Covered Events: Each policy outlines the specific events that trigger coverage. Common examples include fire, theft, vandalism, and certain weather events. It’s important to review your policy details to understand what’s covered.
- Exclusions: BI policies often exclude losses arising from certain events, such as pandemics, power outages, or disruptions in the supply chain. Carefully examine your policy exclusions to avoid any surprises later.
- Policy Limits: The policies have limitations on the amount of income loss or extra expenses they will cover. You must choose coverage limits that adequately reflect your potential losses.
Determining the Right Coverage
Without proper BI coverage, a temporary halt in operations could lead to significant financial losses. Here are some practical steps you can take so your BI coverage serves you well:
Assessing Your Business Needs
Enterprises must conduct a thorough risk assessment to determine the right amount of coverage. This involves evaluating potential risks that could disrupt operations and estimating the potential financial impact. Consider factors like location, industry, and the nature of your operations. High-risk areas prone to natural disasters or industries with critical operational dependencies may require more comprehensive coverage.
Choosing the Right Policy
Selecting the right policy involves understanding the different options available and how they align with your business needs. Policies can vary in terms of coverage limits, exclusions, and premiums. Working with an experienced insurance agent can help you navigate these options and choose a policy that offers adequate protection.
Policy Exclusions and Limitations
It’s important to know what the BI policy does not cover. Common exclusions include damages from non-covered events or losses outside the coverage period. Understanding these limitations can help manage expectations and plan for additional risk management strategies.
Claims Process
Insurance claims can help businesses recover losses from natural disasters or fires so they can have continuity and stability. Here’s a simplified breakdown of the BI claim process:
Documenting the Loss
When filing a claim, businesses need to document their losses thoroughly. This includes providing financial records, proof of the insured event, and evidence of the impact on operations. Accurate and detailed documentation is required for a smooth claims process and to make sure there is fair compensation.
Working with Adjusters
Insurance companies typically assign adjusters to assess the claim. These professionals evaluate the extent of the loss and determine the appropriate amount of compensation. Collaborating closely with adjusters and providing them with the necessary information can expedite the claims process.
Receiving Compensation
Once the claim is approved, enterprises receive compensation based on the policy terms. The funds can be used to cover lost income, pay ongoing expenses, and support recovery efforts. Timely compensation helps businesses manage cash flow and continue operations with minimal disruption.
Tips for Maximizing Coverage
Adequate coverage lets you recover quickly and effectively from incidents such as property damage, theft, or business interruptions. Here are some tips to help you make the most of your insurance policies:
Regular Policy Review
It is important to regularly review and update your business interruption insurance policy. As your business grows and changes, your insurance needs may also evolve. Use periodic reviews so your coverage remains adequate and aligned with your current risk profile.
Maintaining Accurate Records
Keeping detailed and accurate financial records is necessary for business interruption insurance. These records provide the basis for calculating lost revenue and substantiating claims. Ensure that your accounting practices are thorough and up-to-date.
Understanding Your Policy
Fully understand the terms and conditions of your policy to maximize coverage. This includes knowing what is covered, exclusions, and the claim process. Clear policy knowledge can prevent surprises and make sure you can rely on your coverage when needed.
Secure your business’s future with our comprehensive business interruption insurance at Cell Brokerage! Don’t let unforeseen events derail your operations—our expert team will tailor coverage to fit your unique needs. Contact us today for a personalized consultation.
Talk to an Insurance Pro